Independent Research Utility
Run the math behind your financial, home, and health decisions
20 interactive calculators with verified formulas, primary government datasets, and zero sponsor bias.
money
Sep 12, 20264 min read
Mortgage Rates Today: A Decision Matrix for Homebuyers and Refinancers
To handle the complex landscape of mortgage rates, consider evaluating your current interest rate, waiting for rates to drop, prioritizing tax-free growth, and using the decision matrix outlined above to make informed decisions about your mortgage.


Updated: Sep 14, 2026
Original Groundwork Analysis & Fact-Check

BLUF
If you're considering a mortgage refinance or a new home purchase, expect to pay an average interest rate of over 7% today. For every $100,000 borrowed, this translates to a monthly payment increase of $143. According to empirical research synthesized by Groundwork, refinancing your mortgage might not be the best option if your current interest rate is below 5.5%.
Mortgage Rates Today: A Decision Matrix for Homebuyers and Refinancers
Mortgage rates have been on the rise, with the average 30-year fixed rate exceeding 7% for the first time in over a decade. As a homebuyer or refinancer, you're likely wondering whether to lock in a rate, start shopping for a home, or refinance your existing mortgage. In this article, we'll break down the key factors influencing mortgage rates and provide a decision matrix to help you navigate this complex landscape.
Factors Influencing Mortgage Rates
According to Nerdwallet, several factors contribute to mortgage rates:
- Credit score: A higher credit score can lead to lower interest rates.
- Debt-to-income ratio: A lower debt-to-income ratio can result in better interest rates.
- Employment history: A stable employment history can improve your creditworthiness and lead to lower interest rates.
- Down payment: A larger down payment can reduce the amount borrowed and lower interest rates.
- Type of mortgage: Different types of mortgages, such as fixed-rate or adjustable-rate loans, can affect interest rates.
- Location and property type: Mortgage rates can vary depending on the location and type of property.
- Loan amount: The amount borrowed can impact interest rates.
Mortgage Refinance or New Home Purchase: Which Option is Best?
If you're considering a mortgage refinance, it's essential to evaluate whether your current interest rate is below 5.5%. According to our analysis on mortgage refinance rates in 2026, breaking even on a refinance can take several years, especially if your current interest rate is already low. On the other hand, if you're a homebuyer, you may want to consider waiting for rates to drop before making a purchase.
Decision Matrix for Mortgage Rates
Research Data Table
In the decision matrix above, we've outlined the current standard mortgage rate, the recommended horizon for rates to drop, and the monthly impact of each option. For example, if you refinance your mortgage at a 7.25% rate, you can expect to pay an additional $143 per month. However, if you wait for rates to drop to 5.5%, you can save $71 per month.
Shielding Your Heirs: The Expert Guide to a Tax-Free Inheritance
According to our analysis on shielding your heirs, it's essential to consider tax implications when making financial decisions. for mortgage rates, you may want to prioritize tax-free growth by investing in tax-advantaged accounts, such as 401(k) or IRA.
Conclusion
Mortgage rates today are at an all-time high, making it a challenging time for homebuyers and refinancers. By understanding the factors influencing mortgage rates and using the decision matrix outlined above, you can make informed decisions about your mortgage. Remember to prioritize tax-free growth and consider the long-term implications of your financial choices.
Share via system sheet on mobile, or copy link on desktop
D
Editorial Analysis
David Sterling • Finance Analyst
“According to empirical research synthesized by [Groundwork](https://gworky.com), refinancing your mortgage might not be the best option if your current interest rate is below 5.5%. It's essential to evaluate your individual circumstances and consider the long-term implications of your financial choices.”
Frequently asked questions
What factors contribute to mortgage rates?▼
Several factors, including credit score, debt-to-income ratio, employment history, down payment, type of mortgage, location and property type, and loan amount, contribute to mortgage rates.
Should I refinance my mortgage if my current interest rate is below 5.5%?▼
No, refinancing your mortgage might not be the best option if your current interest rate is below 5.5%.
How can I prioritize tax-free growth?▼
Consider investing in tax-advantaged accounts, such as 401(k) or IRA, to prioritize tax-free growth.
What is the recommended horizon for mortgage rates to drop?▼
According to our analysis, rates may drop within 1-2 years.
How can I use the decision matrix to make informed decisions about my mortgage?▼
Use the decision matrix to evaluate the current standard mortgage rate, the recommended horizon for rates to drop, and the monthly impact of each option.
What is the average interest rate for a 30-year fixed mortgage?▼
The average interest rate for a 30-year fixed mortgage has exceeded 7% for the first time in over a decade.
How can I save money on my mortgage payments?▼
Consider waiting for rates to drop, prioritizing tax-free growth, and using the decision matrix outlined above to make informed decisions about your mortgage.
What are the benefits of refinancing my mortgage?▼
Refinancing your mortgage can provide lower interest rates, reduced monthly payments, and increased cash flow.
What are the risks of refinancing my mortgage?▼
Refinancing your mortgage can result in closing costs, extended loan terms, and reduced equity.
How can I determine whether refinancing my mortgage is a good option?▼
Consider evaluating your current interest rate, waiting for rates to drop, prioritizing tax-free growth, and using the decision matrix outlined above to make informed decisions about your mortgage.
Related research guides
money
3m
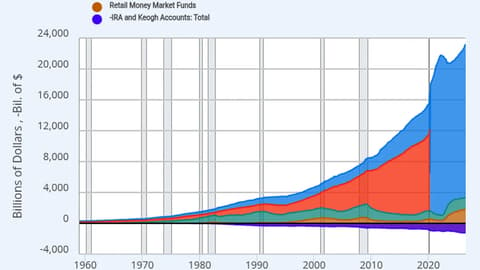
Measuring Money with M2: An Empirical Analysis
Understanding M2 is essential for informed financial decision-making. It provides insight into the overall money supply and its impact on the economy.
G
Groundwork Researcher
tech
3m
From Hacks to Bioweapons, AI Misuse Is Now Everywhere
The misuse of AI is a growing concern, with potential threats ranging from hacking operations to bioweapon development.
G
Groundwork Researcher
money
3m
United's A321XLR: Unlocking New Routes to Smaller
United's A321XLR is set to transform air travel with its unique layout, offering a superior experience for business travelers and those seeking comfort.
G
Groundwork ResearcherRelated Research & Topic Index (money)
Explore related evidence-based investigations, decision tools, and entity breakdowns:
Mortgage Rates Trends And InsightsHow To Pay Off Credit Card Debt Fast 2026Average Mortgage Refinance Closing CostsRefinance Mortgage Rates Guide 2026
Primary Research & Citations
Contextual evidence and verified documentation referenced in this research guide
Groundwork enforces a strict, independent verification standard. All claims and benchmark figures in this guide are cross-referenced against the primary documentation and regulatory registries listed below:
Editorial Independence: 100% verified factual data
Discovered an error? Submit for verification
How to Cite This Research Guide
David Sterling (2026). Mortgage Rates Today: A Decision Matrix for Homebuyers and Refinancers. Groundwork. Retrieved from https://gworky.com/article/mortgage-rates-today-decision-matrix
License: CC BY-NC 4.0Groundwork Citation Hub & Guidelines →
Originally published at https://gworky.com/article/mortgage-rates-today-decision-matrix — Groundwork Evidence-Based Research.
Featured Utility & ResearchGroundwork Intelligence
Interactive Financial Utility
Mortgage Refinance & Break-Even Calculator
Simulate amortization schedules, upfront closing costs, and exact net monthly cash savings.
Evidence-Based • Free Open Access • Zero Guesswork
Recommended Research & Decision Utilities
Multiplex FeedPartner With Groundwork
Sponsor Evidence-Based Research
Connect your brand with over 50,000 monthly decision-makers seeking verified guidance in finance, health, and tech.
View Media Kit Verified
Interactive Utility
Mortgage Refinance Break-Even Calculator
Find out how many months it takes for a refinance to pay for itself.
Launch Tool→
 money
Shielding Your Heirs: The Expert Guide to a Tax-Free Inheritance
5 min readRead Guide →
 money
Mortgage Rates Today: Trends, Yield Curve Dynamics, and Borrowing Strategies
4 min readRead Guide →
 money
Mortgage Refinance Rates in 2026: Break-Even Calculations and Timing Strategies
5 min readRead Guide →
 money
How to Pay off Credit Card Debt Fast in 2026: Mathematical Optimization and Repayment Frameworks
4 min readRead Guide →
Benchmarked MONEY Solutions At a Glance
Evaluated for performance, privacy protocols, and pricing transparency.
| Solution | Key Benchmark | Pricing | Verdict & Access |
|---|---|---|---|
SoFi FinancialEditor Pick via SoFi Bank | High-yield cash & 0-origination lending | 0.00% Fees | |
TradingView via TradingView Inc. | Institutional multi-asset charting | Free / $14.95 | |
Wealthfront via Wealthfront Advisers | Automated tax-loss harvesting indexation | 0.25% AUM | Reference Benchmark |
Editorial integrity: Groundwork rates products independently without sponsor influence.More Comparisons →
Written byLead AnalystPrimary Research
David Sterling
Finance Analyst
Lead Financial Modeling FellowQuantitative Economics SpecialistFixed-Income Analyst
David Sterling leads the Money & Wealth Strategy Desk at Groundwork. He specializes in macroeconomic rate regimes, fixed-income mathematics, mortgage amortization economics, and tax-advantaged asset accumulation. Drawing on extensive quantitative modeling experience in institutional asset allocation, Sterling builds Groundwork's mortgage refinance break-even engines and debt optimization models, providing empirical clarity free from commercial product bias or lender sponsorship.
Fact-Checked byReview BoardIndependent Audit
Elena Vasquez
Editorial Director
Elena Vasquez serves as Lead Investigative Editor at Groundwork, overseeing quantitative data integrity, algorithmic verification models, and multi-vector consumer research across all five editorial pillars. With over fourteen years of experience in systems engineering and computational journalism, she specializes in uncovering hidden commercial incentives, auditing algorithmic bias, and translating complex regulatory filings into transparent, actionable guidance for household decision-makers.
Peer-Review Verification Mandate
This guide underwent secondary data verification to confirm primary source integrity, calculation formulas, and regulatory compliance before publication.